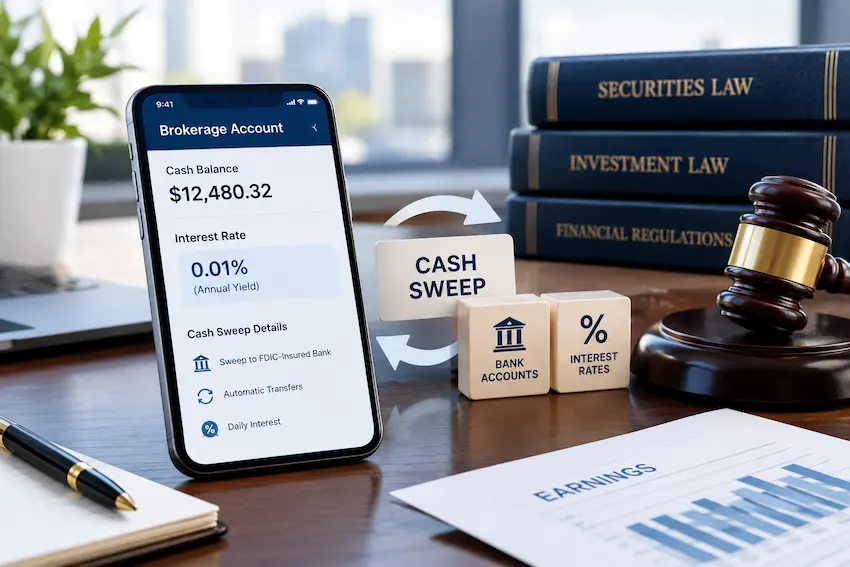
Quick answer. Uninvested brokerage cash may be placed in a bank sweep that pays much less than a money market fund. As of October 17, 2026, Crane Data’s Crane 100 Money Fund Index showed a 3.70% annualized 7-day yield; Crane’s brokerage sweep benchmark for major brokerages was 0.29% using data as of October 9. That is a 3.41-percentage-point gap, or about $1,705 a year on $50,000 if both rates stayed unchanged, before taxes and any additional fees. Your own rate and available options may differ.
Market benchmarks and legal items checked October 18, 2026. Not investment or legal advice.
Cash Drag Calculator
CHECK IT
Enter your average cash balance and comparable annualized rates to estimate the yield gap. The estimate assumes rates stay unchanged and interest is reinvested.
Your result
What Happens to Your Uninvested Cash
CHECK IT
Cash you haven’t invested may remain as a free credit balance, move to a bank deposit through a bank sweep, or be placed in a money market mutual fund through a fund sweep. The available options depend on the brokerage firm and account type.
When you opened the account, the firm typically asked you to pick a cash program. Many people never revisit that choice, so the default can run for years.
Free credit balance. The cash stays in the account as cash. The firm may or may not pay interest on it.
Bank sweep. The firm moves your cash into deposit accounts at one or more banks, usually every day.
Money market fund sweep. The firm moves your cash into a money market mutual fund instead.
Many full-service firms offer only a bank sweep, which can pay far less than a money market fund. Other platforms vary, so check yours.
The default isn’t always the best option on your account.
A default is the firm’s starting point. It isn’t a judgment about what suits your balance or your goals.
Source: FINRA, “Don’t Lose Interest: Managing Cash in Your Brokerage Account”.
Why Sweep Rates Can Be So Low
CHECK IT
Sweep rates can be low because the firm often earns money on the spread between what a bank pays for your deposit and what you receive.
When cash is swept to an affiliated bank, the firm often profits from that spread. That creates a structural incentive to keep the rate you receive low.
FINRA has said the gap between a bank sweep and a money market fund can be as much as 5 percentage points when rates are high. The SEC has said the gap between bank-sweep yields and other sweep options grew to almost 4 percentage points at times as rates rose.
Sweep rates also often depend on balance tier, so a small balance may earn less than a large one. The figures below are broad benchmarks, not a quote for your account.
| Measure | Annualized yield | As of | What it represents |
|---|---|---|---|
| Crane 100 Money Fund Index | 3.70% | Oct. 17, 2026 | 7-day net yield for 100 large taxable money market funds |
| Crane Money Fund Average | 3.60% | Week ended Oct. 9, 2026 | 7-day yield across taxable funds tracked by Crane Data |
| Crane Brokerage Sweep Intelligence Index | 0.29% | Data as of Oct. 9, 2026 | Average FDIC-insured cash options from major brokerages |
| Treasury Retail money funds | 3.44% | Week ended Oct. 9, 2026 | Retail funds in the Treasury category |
For context, the 3.70% Crane 100 yield and the 0.29% brokerage sweep benchmark differ by 3.41 percentage points. On $50,000, that is about $1,705 over one year before taxes and fees if the rates remain unchanged. It is a simple illustration—not a promise that a particular fund or brokerage will pay either rate.
A low sweep rate works like a hidden fee on your balance. For other costs of this kind, see Investment Fees.
Find Your Rate in 3 Minutes
CHECK IT
You can find your sweep rate in about three minutes using your statement, your app, or one message to the firm.
Work through these steps. You can copy the four questions into a chat or read them out on the phone.
- Find your cash line. On your statement or app, look for “cash,” “core position,” “sweep,” or “bank deposit program,” and note the balance.
- Find the rate. Check the statement or the firm’s sweep disclosure for the current rate on your balance tier.
- Ask four questions (chat or phone):
- “What rate is my uninvested cash earning today, and at what balance tier?”
- “What other cash options does this account offer — can a money market fund be my sweep, or can I buy one?”
- “Are there minimums, fees, or trading restrictions on those options?”
- “How is my swept cash protected, and where is the program bank list?”
- Decide. Switch the sweep option, buy a money fund for larger balances, or keep the bank sweep if FDIC coverage matters more to you.
- Check IRAs and rollovers separately. Each account has its own setting.
- Re-check every quarter, or when rates change.
Write down the rate, the balance, and the date. You’ll need all three to compare later.
Your Options Inside the Same Account
CHANGE IT
Inside most accounts you can leave cash as it is, switch the sweep, or buy a money market fund yourself, and each trades yield against protection.
| Option | How it works | Protection | Liquidity | What to check |
|---|---|---|---|---|
| Free credit balance | Cash stays in the account as cash. | SIPC if the broker fails and assets are missing; not FDIC. | Available on normal brokerage timelines. | Whether it pays interest at all. |
| Bank sweep | Cash moves daily into deposit accounts at one or more banks. | FDIC pass-through insurance, subject to conditions; not SIPC. | Available on normal brokerage timelines. | Rate by balance tier, program bank list, coverage limits. |
| Money fund sweep | Cash moves daily into a money market fund. | Not FDIC-insured. Fund shares are securities held at the broker (SIPC for missing assets, not investment loss). | Sale and withdrawal timing depend on cutoffs, settlement and broker rules. | Fund type, 7-day yield, expenses, prospectus. |
| Money fund bought manually | You buy fund shares with the cash yourself. | Same as a money fund sweep. | Sale and withdrawal timing depend on cutoffs, settlement and broker rules. | Minimums, separate account fees, and what happens to new cash that arrives later. |
Changing the automatic sweep, when your firm offers another eligible option, changes where future idle cash is routed under that program’s rules.
Buying a money fund manually is a separate trade. Unless the account’s automatic sweep is also changed, newly arriving cash may continue to land in the default position.
A bank sweep can still make sense if FDIC coverage matters more to you than yield, or if the balance is small enough that the dollar gap is minor. The calculator above shows the gap for your numbers.
Money market funds aren’t FDIC-insured.
Some money market funds can impose liquidity fees in specified circumstances, and the rules differ by fund type. Redemption timing and settlement can also depend on your broker, trade cutoffs and the fund’s prospectus.
For the wider comparison of where to keep cash outside a brokerage account, see Where to Park Cash in 2026.
FDIC vs. SIPC: How Each Option Is Protected
KNOW YOUR RIGHTS
Qualifying bank-sweep deposits may receive FDIC pass-through insurance, money market fund shares are not FDIC-insured, and SIPC protection addresses missing customer cash or securities if a SIPC-member brokerage fails—not market losses.
Bank sweep
FDIC: Eligible for pass-through insurance, subject to conditions.
SIPC: No. Swept bank deposits aren’t SIPC-protected.
Limit: $250,000 per program bank, per ownership category. Your own deposits at that bank count toward it.
Conditions: Records must show you as the owner. Opting out of a program bank may reduce coverage.
Doesn’t cover: Balances above the limit at any one bank.
Money market fund
FDIC: No.
SIPC: Fund shares are securities held at the broker, so SIPC applies if a failed broker’s assets are missing.
Limit: $500,000 per customer per capacity, securities and cash combined.
Conditions: The broker must be a SIPC member.
Doesn’t cover: Investment loss, including a fall in the fund’s share value.
Free credit balance
FDIC: No.
SIPC: Yes, if the broker is a SIPC member and assets are missing.
Limit: $500,000 per customer per capacity, of which up to $250,000 can be cash.
Conditions: Interest may or may not be paid.
Doesn’t cover: Market losses, or amounts above the limits.
| Feature | Bank sweep | Money market fund | Cash at the broker |
|---|---|---|---|
| FDIC? | Eligible for pass-through insurance, subject to conditions | No | No |
| SIPC? | No | Yes, for missing assets if a SIPC-member broker fails (fund shares are securities) | Yes, for missing assets if a SIPC-member broker fails |
| Limit | $250,000 per program bank, per ownership category | $500,000 per customer per capacity, securities and cash combined | $500,000 per customer per capacity, of which up to $250,000 can be cash |
| Conditions | Records must show you as the owner; your own deposits at a program bank count; opting out of a program bank may reduce coverage | Broker must be a SIPC member | Broker must be a SIPC member; interest may or may not be paid |
| What it doesn’t cover | Balances above the limit at any one bank | Investment loss, including a fall in share value | Market losses; amounts above the limits |
Pass-through conditions people miss
The limit applies per program bank. It is $250,000 per program bank per ownership category, not per firm.
Funds may be spread across several program banks. That can raise the total you have insured. Ask for the program bank list.
Your own deposits count. If you also bank directly with one of the firm’s program banks, those deposits count toward the same limit.
Conditions apply. Pass-through coverage depends on the deposit records showing you as the owner. Also ask whether the program caps the total it will place with its banks.
Swept bank deposits aren’t SIPC-protected. SIPC protects securities and cash held at the broker, up to $500,000 per customer per capacity, including up to $250,000 of cash. It doesn’t protect against investment losses.
Opting out of a program bank can lower your FDIC coverage.
Your cash is then spread across fewer banks. Ask how much of your balance would stay insured before you opt out.
For limits by ownership category, see FDIC Insurance Limits. For what SIPC does and doesn’t cover, see SIPC Coverage Limits.
Advisory vs. Self-Directed: Why It Matters
KNOW YOUR RIGHTS
The duties that apply to cash management can differ depending on whether the account is an advisory relationship or a self-directed brokerage account.
A registered investment adviser generally owes fiduciary duties in the advisory relationship. Broker-dealer obligations differ and may depend on whether the firm made a recommendation, the applicable standards and the account agreement. Check your account paperwork; labels alone do not resolve every legal question.
| Account type | Standard owed | What it means for cash | What to ask |
|---|---|---|---|
| Advisory (managed) | A registered investment adviser owes duties of care and loyalty. | The SEC’s 2025 actions concerned how firms chose sweep options for advisory accounts. Managing client cash is part of the adviser’s role. | “How did you review the cash options for my account? Does my advisory fee apply to cash?” |
| Self-directed brokerage | Generally narrower. Courts have treated these accounts differently from advisory ones, with mixed results. | The default cash program usually comes from the account agreement. Alternatives are yours to ask for. | “What does my account agreement say about the cash program and rate, and which other options can I choose?” |
On January 17, 2025, the SEC announced settled charges against two Wells Fargo advisory firms and Merrill Lynch concerning cash-sweep policies for advisory clients. The SEC’s orders said the firms had failed to adopt and implement policies reasonably designed to consider clients’ best interests when evaluating which sweep options to offer. The civil penalties were $28 million, $7 million and $25 million, respectively. The firms settled without admitting or denying the SEC’s findings.
That record is about advisory accounts. It doesn’t tell you how a court would treat a self-directed account, where results have been mixed.
For the broader difference between fiduciaries and brokers, see Fiduciary vs. Broker.
IRAs and Rollovers
CHECK IT
Cash often sits unnoticed in IRAs, especially after a rollover, because each account has its own cash setting.
A common scenario: you roll a 401(k) into an IRA, the money arrives as cash, and it stays in the sweep until you invest it.
Each IRA has its own sweep setting, so check every account separately. Contributions you haven’t invested yet land in the same place.
Roth IRA. Qualified growth is generally tax-free, so low sweep interest is lost tax-free growth.
Traditional IRA. Growth is tax-deferred, so low sweep interest is lost tax-sheltered growth that would have compounded.
The calculator above shows the difference for IRA accounts too. For the rollover steps themselves, see 401(k) to IRA Rollover.
What the Lawsuits and Settlements Changed
KNOW YOUR RIGHTS
Since 2022, regulators and courts have produced a mix of settlements, closed regulatory inquiries and pending private cases. These developments do not automatically change the rate paid on your account today, and an allegation or settlement is not proof that every brokerage sweep program is unlawful.
The practical value is that they show which questions are worth asking. The scoreboard below lists each item with its date and status.
2022 — Schwab
Action: SEC settlement requiring Schwab adviser subsidiaries to pay $187 million to harmed clients over disclosures about cash allocations in Schwab Intelligent Portfolios, its robo-adviser program. This was a related cash-allocation matter, not a finding about every Schwab brokerage sweep account.
Status: Settled.
Jan. 17, 2025 — Wells Fargo advisory firms and Merrill Lynch
Action: SEC settled charges that they failed to consider clients’ best interest when choosing sweep options for advisory accounts. Penalties: $28 million, $7 million and $25 million. No admission or denial of the findings.
Status: Settled.
May 2025 — Morgan Stanley
Action: Morgan Stanley disclosed that the SEC closed its inquiry into the advisory cash sweep program without recommending enforcement action.
Status: SEC inquiry closed. Separate cash-sweep class-action litigation remained pending in company disclosures filed in 2026; closure of the SEC inquiry did not decide those private claims.
Jan. 23, 2026 — LPL
Action: SEC concluded its inquiry into LPL’s corporate advisory cash program without recommending action.
Status: SEC inquiry closed. Private lawsuits continue.
Feb. 2026 — JPMorgan
Action: A federal judge in Manhattan allowed contract claims concerning JPMorgan’s cash-sweep rates to proceed, while dismissing fiduciary-duty and best-interest claims at that stage.
Status: Pending. The allegations are unproven, and the ruling was not a final finding of liability.
2026 — Oppenheimer
Action: $70 million class settlement for eligible Advantage Bank Deposit Program participants during the class period March 17, 2022–May 22, 2026. Oppenheimer did not admit liability or wrongdoing.
Status: Final approval and judgment entered September 18, 2026. The claim deadline was September 17, 2026, and has passed.
Sept. 30, 2026 — Merrill Lynch
Action: Preliminary $39 million class settlement concerning alleged low rates on idle cash for a defined group of Merrill Edge online account holders from December 15, 2016–March 15, 2020. Merrill denied wrongdoing.
Status: The agreement was filed September 30, 2026 and requires court approval. Check the court docket and any official notice for the final class definition and claim instructions.
| Date | Firm | Action | Status |
|---|---|---|---|
| June 13, 2022 | Schwab adviser subsidiaries | SEC settlement: $187 million for harmed clients over disclosures about cash allocations in Schwab Intelligent Portfolios, a robo-adviser program | Settled; related context, not a ruling on every brokerage sweep account |
| Jan. 17, 2025 | Wells Fargo advisory firms and Merrill Lynch | SEC settled charges: failed to consider clients’ best interest when choosing sweep options for advisory accounts. Penalties of $28 million, $7 million and $25 million; no admission or denial of the findings | Settled |
| May 2025 | Morgan Stanley | Company disclosed the SEC closed its inquiry into the advisory cash sweep program without recommending enforcement action | SEC inquiry closed; separate cash-sweep litigation remained pending in company disclosures filed in 2026 |
| Jan. 23, 2026 | LPL | SEC concluded its inquiry into the corporate advisory cash program without recommending action | SEC inquiry closed; private lawsuits continue |
| Feb. 13, 2026 | JPMorgan | Judge allowed certain contract claims about cash-sweep rates to proceed, while dismissing fiduciary-duty and best-interest claims at that stage | Pending; allegations unproven; no final liability finding |
| Sept. 18, 2026 | Oppenheimer | $70 million settlement for eligible Advantage Bank Deposit Program participants in the March 17, 2022–May 22, 2026 class period; no admission of liability | Final approval and judgment entered; claim deadline Sept. 17, 2026 has passed |
| Sept. 30, 2026 | Merrill Lynch | Preliminary $39 million settlement over alleged low rates on idle cash for a defined Merrill Edge online-account class, Dec. 15, 2016–Mar. 15, 2020; Merrill denied wrongdoing | Filed in court; approval required. Follow the docket and official notice for class details and claim instructions |
The LPL inquiry concerned advisory accounts, and the JPMorgan case is still pending. Neither one shows how self-directed accounts are protected.
The Oppenheimer settlement is a precedent, not an opportunity. Claims closed on Sept. 17, 2026.
The Merrill settlement is limited. The September 2026 agreement is preliminary, covers a defined class and still needs court approval. A separate case involving broader allegations about retirement and non-retirement accounts remained active when Reuters reported the settlement.
How to verify a settlement
Read the official notice and confirm the case on the court docket. Use only the court-appointed settlement administrator identified in the notice. For Oppenheimer, the administrator website was OppenheimerCashSweepLitigation.com; the claim deadline has passed. For the Merrill agreement reported September 30, 2026, check the docket for approval, the final class definition and any official claim instructions before taking action.
Never pay anyone to “register” you for a settlement.
Anyone charging a fee to register you for a cash sweep settlement fits a known scam pattern. Claims go through the court-appointed administrator named in the official notice.
Taxes on Sweep Interest
KNOW YOUR RIGHTS
Interest on swept cash in a taxable account is generally ordinary income, and in an IRA the cost is lost tax-sheltered growth instead.
Money market mutual funds generally report distributions as dividends, while bank-sweep interest is generally reported as interest income. Federal tax treatment depends on the income type, and some Treasury-related fund distributions may qualify for a state income-tax exemption. The eligible portion and reporting treatment depend on the fund and your state.
See the IRS Publication 550, Investment Income and Expenses for federal tax treatment of interest and money market fund distributions, and check your state’s rules or ask a tax professional about state exemptions.
FAQ
What is a cash sweep?
A cash sweep is a program that moves uninvested cash in your brokerage account into a bank deposit account or a money market fund, usually each day.
Why is my sweep rate so low?
Often because the firm earns a spread on swept bank deposits, and many full-service firms offer only a bank sweep. See why sweep rates can be so low.
How do I find my sweep rate?
Check your statement or the firm’s sweep disclosure for the rate at your balance tier, or ask. The 3-minute audit walks through it.
Can I change my cash sweep option?
Often, yes, but the options depend on the firm and account type. Ask which options your account offers and whether minimums, fees, or trading restrictions apply.
Is it better to buy a money market fund?
Not for everyone. Crane Data’s Crane 100 Money Fund Index showed a 3.70% annualized 7-day yield as of October 17, 2026, but a particular fund’s yield, expenses and availability can differ. A fund is not FDIC-insured, so weigh yield, liquidity, fees and risks against the protections of your current option.
Is my swept cash FDIC-insured?
Bank sweeps are eligible for pass-through FDIC insurance up to $250,000 per program bank per ownership category, subject to conditions. Swept bank deposits aren’t SIPC-protected.
What does “pass-through” FDIC coverage mean?
Coverage passes through the firm to you as the owner of the deposits, as long as the FDIC’s recordkeeping conditions are met.
What happens if I opt out of a program bank?
Coverage may fall, because your cash is spread across fewer banks. Ask how much of your balance would stay insured and where the rest would go.
Are money market funds safe?
They invest in short-term instruments but are not FDIC-insured or guaranteed. Some retail and government money market funds seek to maintain a stable $1 share price, while institutional prime and institutional tax-exempt funds generally use a floating net asset value. Government and Treasury funds hold government or Treasury-related instruments; prime funds can hold other short-term debt. Read the prospectus for risks, fees and redemption terms.
Does SIPC protect my cash?
SIPC covers cash and securities missing from a failed member broker, up to $500,000 per customer per capacity, including up to $250,000 of cash. It doesn’t cover investment losses, and swept bank deposits fall under FDIC rules instead.
Does it matter if my account is advisory or self-directed?
It can. Registered investment advisers generally owe fiduciary duties within the advisory relationship, while broker-dealer duties differ and can depend on whether a recommendation was made. The January 2025 SEC actions concerned cash-sweep policies for advisory accounts; they do not automatically resolve every self-directed account claim. See advisory vs. self-directed.
Why is cash sitting in my IRA after a rollover?
Rolled-over money usually arrives as cash and stays that way until you invest it. Check the sweep setting on the IRA itself.
What did the SEC do about cash sweeps?
On January 17, 2025, the SEC announced settled charges against two Wells Fargo advisory firms and Merrill Lynch over their cash-sweep policies for advisory accounts. Morgan Stanley disclosed that the SEC closed its inquiry without recommending enforcement action in May 2025, and LPL disclosed on January 23, 2026 that the SEC did not intend to recommend an enforcement action after its inquiry. Separate private lawsuits may continue; a closed SEC inquiry is not a court ruling that a program’s rates were reasonable.
Am I part of the Merrill cash sweep settlement?
The September 30, 2026 report describes a preliminary $39 million settlement involving a defined class of Merrill Edge online account holders during December 15, 2016–March 15, 2020, over alleged low rates on idle cash in retirement accounts. Merrill denied wrongdoing, and the agreement requires court approval. The class definition and any claim steps must be confirmed from the official court notice; this is not a settlement for all Merrill clients.
Can I still claim from the Oppenheimer settlement?
The claim deadline was September 17, 2026, and final approval and judgment were entered September 18, 2026. That deadline has passed. The official settlement website may still contain case documents, but do not pay anyone who claims they can reopen the deadline.
How do I spot a fake settlement claim?
Confirm the case name and administrator in the official notice or court docket, and use only contact details listed there. Treat unsolicited texts or messages promising guaranteed settlement money as suspicious. See how to verify a settlement.
Is sweep interest taxable?
Bank-sweep interest in a taxable account is generally taxable interest income. Money market mutual fund distributions are generally reported as dividends, with tax treatment depending on the type of distribution. Inside an IRA, earnings generally aren’t taxed annually, though traditional IRA withdrawals may be taxable and Roth IRA withdrawals must meet applicable rules. See taxes on sweep interest.
Should I move brokers over a low sweep rate?
Usually try changing the cash option inside the account first. If you do decide to move, see Best Online Stock Brokers and Transfer Stocks Without Selling.
Last updated:
This article is general information, not investment or legal advice. Yields change daily and vary by firm and balance. Legal items were verified on October 18, 2026. Protection depends on program terms and conditions.
Daniel Hayes is the founder and sole researcher at AdvoraHQ. He covers U.S. personal finance, insurance, and consumer law — working directly from IRS publications, federal and state statutes, court opinions, and SEC filings rather than secondary summaries. His focus is the gap between what readers think they know and what the source documents actually say. Daniel is not a licensed attorney, CPA, or financial advisor; his articles are educational and not personalized advice. Reach him at Daniel.Hayes@advorahq.com.