
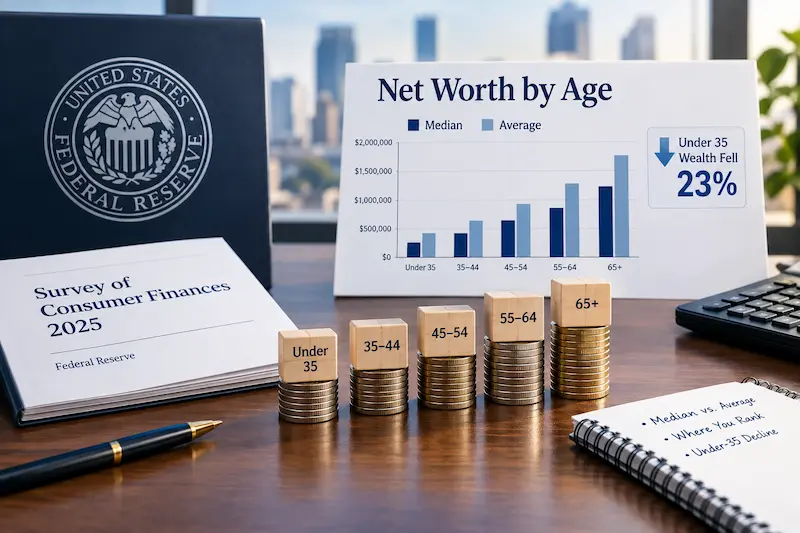
See your net worth and how it compares to your age group →
- By age
- Median vs. average
- Why under-35 fell
- Owners vs. renters
- Wealth groups
- What counts
- Why sources disagree
Source: Federal Reserve, Survey of Consumer Finances 2025 (Oct. 2026). All figures in 2025 dollars. Next survey expected 2028–2029.
Net Worth Calculator (Fed Definition)
This calculator adds up what you own, subtracts what you owe, and compares the result with the Fed’s 2025 medians and averages. Nothing you type leaves your device.
The Fed measures families, so couples should enter combined totals.
Net Worth by Age: The New 2025 Numbers
The Fed’s 2025 survey puts the median family net worth at $215,900 overall, ranging from a median of $33,000 for families under 35 to $504,900 for families 75 and older.
The survey interviewed 4,367 families in 2025 (4,602 in 2022). Age means the age of the family’s reference person, and net worth is measured at the time of the interview.
-
Under 35
WHAT’S TYPICAL: median $33,000, down 23% from 2022
WHAT’S SKEWED: average $135,400, down 33%
-
35–44
WHAT’S TYPICAL: median $155,600, up 5%
WHAT’S SKEWED: average $681,900, up 13%
-
45–54
WHAT’S TYPICAL: median $253,700, down 6%
WHAT’S SKEWED: average $1,244,500, up 17%
-
55–64
WHAT’S TYPICAL: median $411,900, up 3%
WHAT’S SKEWED: average $1,878,000, up 10%
-
65–74
WHAT’S TYPICAL: median $431,300, down 4%
WHAT’S SKEWED: average $1,897,600, down 3%
-
75 and older
WHAT’S TYPICAL: median $504,900, up 37%
WHAT’S SKEWED: average $1,962,200, up 10%
Bars are scaled to the largest average ($1,962,200). Changes compare 2025 with 2022 restated in 2025 dollars.
| Age | Median 2022 | Median 2025 | Change | Average 2022 | Average 2025 | Change |
|---|---|---|---|---|---|---|
| Under 35 | $42,700 | $33,000 | −23% | $200,800 | $135,400 | −33% |
| 35–44 | $148,400 | $155,600 | +5% | $601,500 | $681,900 | +13% |
| 45–54 | $270,600 | $253,700 | −6% | $1,067,900 | $1,244,500 | +17% |
| 55–64 | $398,900 | $411,900 | +3% | $1,714,700 | $1,878,000 | +10% |
| 65–74 | $448,600 | $431,300 | −4% | $1,963,900 | $1,897,600 | −3% |
| 75 and older | $367,300 | $504,900 | +37% | $1,777,400 | $1,962,200 | +10% |
| All families | $211,100 | $215,900 | +2% | $1,164,100 | $1,241,500 | +7% |
Under 35. The median is $33,000, down 23%. The Fed ties the drop mainly to business equity gains unwinding after 2019–2022 (more below).
35–44. The median is $155,600, up 5%. The average rose 13%, faster than the median, which the Fed says usually signals bigger gains near the top of the group.
45–54. The median is $253,700, down 6%, while the average rose 17% to $1,244,500. The typical family slipped even as values at the upper end climbed.
55–64. The median is $411,900, up 3%, and the average is $1,878,000, up 10%.
65–74. The median is $431,300, down 4%. The Fed notes that nearly retired and recently retired families saw some declines in this survey.
75 and older. The median is $504,900, up 37%, the largest of any age group in this survey. The Fed credits retirement account values.
These are group medians and averages, and the families in them have very different incomes, costs and household sizes. They describe what is typical, not what you should have.
The 2025 survey is a snapshot of different families than the 2022 one, so it doesn’t follow the same people through time. For retirement accounts alone, see Average Retirement Savings by Age.
Median vs. Average: Which Number Is “You”?
For most families the median is the better comparison, because the average is pulled up by a small group of very wealthy families.
Across all families, the average net worth ($1,241,500) is about 5.75 times the median ($215,900).
The Fed designs the survey to capture families across the whole wealth range, including families with extremely high wealth. Its report explains that medians are less sensitive to very large values, while averages are handy for comparing groups.
The Fed also notes that medians don’t add up. Median assets minus median debts won’t equal median net worth, so don’t try to build your benchmark that way.
Why Net Worth Fell 23% for Families Under 35
The Fed says the decline is primarily driven by the unwinding of business equity gains between 2019 and 2022.
Across all families, the median value of business equity among owners fell 23% to $75,400, while the share owning a private business edged up to 15.4%. That is a family-wide figure, not an under-35 one.
Younger families were also saving for retirement more often. Participation in IRAs or employer plans among under-35 families rose from 42% in 2016 to nearly 50% in 2025.
The Fed’s Box 2 also shows that the average combined balance in these accounts rose for every age group except the youngest.
What this doesn’t mean. It doesn’t mean every young family lost wealth. The survey compares two different groups of families, so it can’t tell you what happened to the same people over three years.
If you are under 35 and below the median, you are in a large group. How to Get Out of Debt and How Much Emergency Fund are good next reads.
Why Families 75 and Older Are Now on Top
Families 75 and older now have the highest median net worth ($504,900), and the Fed says the rise was primarily driven by an increase in the value of retirement accounts.
Their median is up 37% from $367,300 (2022, in 2025 dollars). Their average is $1,962,200, up 10%.
In the last few surveys, families near or at retirement had the largest net worth. This time 75 and older moved ahead of them, within this survey.
The Fed also flags a composition note: the share of families in the 75-and-older group grew in 2025. In theory that could shift the numbers, but the Fed says retirement account values were the main driver.
Planning for your own later years? See Retirement Planning by Age and How Much Money Do You Need to Retire.
Homeowners vs. Renters
Homeowners have a median net worth of $458,900, while renters and other non-homeowners have a median of $10,600.
| Group | Median 2025 | Change from 2022 | Average 2025 |
|---|---|---|---|
| Homeowners | $458,900 | +6% | $1,812,900 |
| Renters or other | $10,600 | −7% | $153,500 |
| Metro areas | $231,300 | +6% | $1,337,700 |
| Non-metro areas | $150,100 | −6% | $577,100 |
The homeownership rate was 66% in 2025, about unchanged. For owners, the median net housing value (home value minus home-secured debt) rose to $230,000 from $218,900.
Owners and renters differ in more than housing. In the Fed’s income table, median family income was $108,900 for owners and $50,300 for renters in the year before the survey.
Housing was also less affordable. The median home was worth more than 4.5 times the median family income, and the Fed puts the monthly payment on the median home at about 33% of median monthly family income, up from 26% in 2022. That estimate assumes a 30-year fixed mortgage covering 80% of the price and property taxes of 1% of the home’s value a year.
Thinking about buying or paying down a mortgage? See How Much House Can I Afford and Pay Off Mortgage or Invest.
The Fed’s report also breaks results out by race, ethnicity and education. Those figures need the Fed’s full context, so read them in the report itself.
The Wealth Groups: Bottom 25% to Top 10%
The Fed splits families into wealth groups, and the median within the bottom 25% was $1,700 in 2025 while the median within the top 10% was $4,935,200.
| Wealth group | Median 2022 | Median 2025 | Change |
|---|---|---|---|
| Bottom 25% | $3,800 | $1,700 | −56% |
| 25th to 49.9th percentile | $102,100 | $100,900 | −1% |
| 50th to 74.9th percentile | $389,900 | $405,700 | +4% |
| 75th to 89.9th percentile | $1,134,000 | $1,267,500 | +12% |
| Top 10% | $4,152,700 | $4,935,200 | +19% |
This page does not estimate your percentile. The Fed publishes percentile cutoffs in Appendix A of its report (“Percentiles of the Distributions of Income and Net Worth”).
The bottom 25% group also had a negative average net worth of −$4,300 in 2025, meaning debts exceeded assets for the group on average.
Some news coverage cites $3.6 million for “the richest tenth.” That figure is the median net worth of the top tenth by income, not by wealth. The Fed gives it as $3,669,900, up 31%.
What Counts as Net Worth — and What the Fed Leaves Out
The Fed counts most things you own, including your home, retirement accounts and business, minus your debts, but it leaves out Social Security, employer defined-benefit pensions and employee stock options.
| Item | Counted? | Note |
|---|---|---|
| Cash and bank accounts | Yes | Checking, savings, money market, CDs and prepaid cards. The Fed’s savings category includes health savings and 529 accounts. |
| Retirement accounts | Yes | IRAs, 401(k), 403(b) and TSP accounts, including accounts from past jobs that you expect to receive. |
| Home equity | Yes | Home value minus mortgages and HELOCs. Other real estate is counted too. |
| Vehicles | Yes | Cars, trucks, motorcycles, boats, RVs and similar. |
| Business equity | Yes | Private business value, net of business debts. Debt on nonresidential property is netted against that property. |
| Crypto | Yes | Counted in the Fed’s “other financial assets.” |
| Cash-value life insurance | Yes | Current cash value only. Term insurance has none. Annuities count only when you have an equity interest. |
| Social Security | No | The Fed says future income streams can’t be easily translated into a current value. |
| Employer defined-benefit pension | No | Same reason as Social Security. |
| Employee stock options | No | Generally excluded, except stock option retirement plans. |
| Debts | Subtracted | Mortgages, HELOCs, student loans, vehicle loans, credit card balances, other installment loans and other debt. |
“Credit card balances” means what you carry after your last payment, not what you charged this month. Net worth is measured at the time of the interview.
Because Social Security and pensions are left out, these figures can’t tell you how secure any group’s retirement income is. The retirement-account piece alone is in Average Retirement Savings by Age.
Why Every Net Worth Chart Gives a Different Number
Net worth figures disagree because they come from different people, in different years, measured in different dollars.
| Source | Who’s measured | Representative? | Date | Dollars |
|---|---|---|---|---|
| Fed Survey of Consumer Finances 2025 | 4,367 families, interviewed in 2025 | Yes. Designed to represent U.S. families. | Released Oct. 9, 2026 | 2025 dollars |
| App-user dashboards (for example, Empower) | People who use the company’s app | No. Empower says its figures aren’t comparable to representative surveys. | Varies by publication | As of each snapshot |
| Pages still citing SCF 2022 | 4,602 families, interviewed in 2022 | Yes, but older. | Released Oct. 2023 | 2022 dollars (under-35 median shown as $39,000) |
Empower’s figures come from its own app users, and Empower notes they are not comparable with representative surveys. This page uses the Fed survey only.
Many pages with “2026” in the title still show the 2022 survey. They show the 2022 median of $39,000 for under-35, while the same number restated in 2025 dollars is $42,700.
How to Move Up From Where You Are
A sensible order for most people is to handle costly debt, build a cash cushion, capture any retirement match, and then invest.
This isn’t a target or a promise. Benchmarks describe other families, not what you should have, and your income, costs and household size matter more than any median.
Money is tighter for many families. The Fed found the share of families late on loan payments rose from 12.2% to 19.6% between 2022 and 2025.
Debt is common, so you are not alone. About 77% of families had some debt in 2025. Among families carrying credit card balances, the median balance was $3,100, and the 20% with student debt had a median balance of $25,600.
1. Debt. Start with How to Get Out of Debt.
2. Cushion. Size your reserve with How Much Emergency Fund, and find the room in your pay with How to Make a Budget.
3. Retirement. See How Much Money Do You Need to Retire and Retirement Planning by Age.
4. Invest. Read How to Build an Investment Portfolio.
Net Worth Worksheet
Fill this in on paper or paste it into a notes app: add up what you own, subtract what you owe, and date the result.
NET WORTH WORKSHEET
Date: ____________   (recheck every 6-12 months)

WHAT I OWN
Cash (checking, savings, money market, CDs): $________
Retirement accounts: $________
Investments (brokerage, crypto): $________
Home value: $________
Other real estate: $________
Vehicles: $________
Business equity: $________
Other assets: $________
Total owned: $________

WHAT I OWE
Mortgage / HELOC: $________
Other real estate loans: $________
Car loans: $________
Student loans: $________
Credit card balances: $________
Other debt: $________
Total owed: $________

NET WORTH = Owned - Owed = $________

Not counted here (but it matters): expected Social Security, pension, future inheritance.
A snapshot, not financial advice.
FAQ
Short answers on net worth by age, based on the Fed’s 2025 survey (released Oct. 9, 2026, in 2025 dollars).
What is the median net worth by age in 2026?
The newest Fed survey gives a median of $33,000 for under 35, $155,600 for 35–44, $253,700 for 45–54, $411,900 for 55–64, $431,300 for 65–74 and $504,900 for 75 and older. The median for all families is $215,900.
What is the average net worth for someone under 35?
The average is $135,400, down 33% from 2022. The median, which is the better comparison, is $33,000.
What is a good net worth at 30? At 40? At 50?
The Fed doesn’t define “good,” and the survey uses age bands rather than exact ages. As reference points, the median is $33,000 for under 35, $155,600 for 35–44 and $253,700 for 45–54. They are descriptions of typical families, not targets.
What is the median net worth for ages 55–64?
The median is $411,900, up 3% from 2022. The average is $1,878,000.
What is the net worth of the average retiree?
The Fed doesn’t report retirees as a group. For ages 65–74, the median is $431,300 and the average is $1,897,600. For 75 and older, the median is $504,900 and the average is $1,962,200. Social Security and pensions aren’t counted.
Why is average net worth so much higher than median?
A small number of very wealthy families pull the average up. Overall, the average ($1,241,500) is about 5.75 times the median ($215,900).
Why did young Americans’ net worth drop?
The Fed says the declines for families under 35 are primarily driven by the unwinding of business equity gains between 2019 and 2022. The median fell 23% to $33,000.
Why are people 75 and older the wealthiest age group now?
The Fed says the median increase (+37% to $504,900) was primarily driven by higher retirement account values. They are the top age group in this survey, unlike the last few.
Does net worth include home equity?
Yes. The Fed counts the home’s value minus mortgages and HELOCs. Our calculator also shows your net worth without home equity.
Does net worth include my 401(k)?
Yes. IRAs, 401(k), 403(b) and TSP accounts count.
Is Social Security counted in net worth?
No. The Fed excludes Social Security and employer defined-benefit pensions, saying future income streams can’t be easily translated into a current value.
What net worth is top 10%?
This page doesn’t give a cutoff. The median within the Fed’s top-10% group is $4,935,200, but that is the middle of the group, not the entry point. The cutoffs are in Appendix A of the Fed’s report.
What’s the median net worth of renters?
The median for renters and other non-homeowners is $10,600, down 7%. The average is $153,500.
How often does the Fed update these numbers?
Every three years. The 2025 survey was released Oct. 9, 2026, and the next is expected 2028–2029.
Why do Empower’s numbers differ?
Empower’s figures come from its own app users, and Empower notes they are not comparable with representative surveys. Some older pages also show 2022 numbers in 2022 dollars.
Should a couple count combined net worth?
Yes. The Fed measures families, so use combined totals. The age group is the age of the family’s reference person.
Is negative net worth normal?
It isn’t unusual in the lowest group. The Fed reports an average net worth of −$4,300 for the bottom 25% group, though the median there is positive at $1,700. It’s a snapshot that can change.
How do I increase my net worth?
Work through the steps above: debt, cash cushion, retirement match, then investing. No order is a guarantee, and your situation matters more than any benchmark.
Sources
Federal Reserve Board, Changes in U.S. Family Finances from 2022 to 2025: Evidence from the Survey of Consumer Finances (October 2026), Tables 1–2 and Appendix A.
Federal Reserve press release, October 9, 2026.
Survey of Consumer Finances data page and interactive chartbook.
Empower, The average net worth by age in America (for its own comparability note).
Disclaimer: This page is general information, not financial advice. Figures come from the Federal Reserve’s 2025 Survey of Consumer Finances (released Oct. 9, 2026), in 2025 dollars, and individual circumstances vary. Last updated: .

Daniel Hayes is the founder and sole researcher at AdvoraHQ. He covers U.S. personal finance, insurance, and consumer law — working directly from IRS publications, federal and state statutes, court opinions, and SEC filings rather than secondary summaries. His focus is the gap between what readers think they know and what the source documents actually say. Daniel is not a licensed attorney, CPA, or financial advisor; his articles are educational and not personalized advice. Reach him at Daniel.Hayes@advorahq.com.
