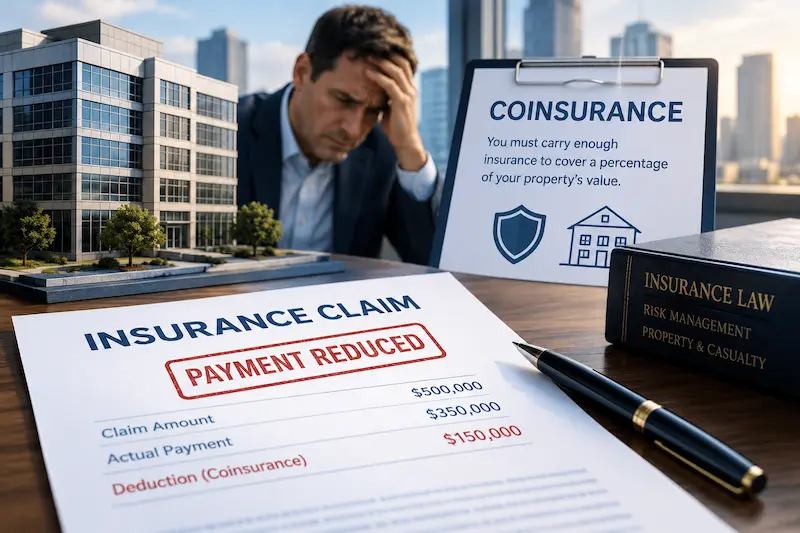
Your building is insured for $600,000. The fire did $100,000 in damage. Nothing came close to your limit. The check is for $75,000, minus your deductible — and the policy was applied correctly.
A clause most owners have never read measures your limit against what the building is worth on the day of the loss — not against the size of your claim.
Check your own policy against it → Jump to the calculator
Coinsurance Penalty Calculator
Enter the figures from your policy and a professional rebuild-cost estimate. This tool cannot value your building — a market value, a book value, or a tax assessment will produce a meaningless result here.
Three lines on your declarations page decide this: the coinsurance percentage, whether Agreed Value is in effect, and whether replacement cost was selected.
Based on the ISO Building and Personal Property Coverage Form; verified October 2026. Your own policy may be written differently — read it.
What the Clause Actually Says
The coinsurance condition compares two numbers that have nothing to do with the size of your claim: what you’re carrying, and what the policy requires you to carry.
“Insurance carried” is your limit of insurance — the dollar figure on your declarations page. “Insurance required” is your property’s value at the time of loss, multiplied by the coinsurance percentage also shown on your declarations, usually 80%, 90%, or 100%.
If what you’re carrying meets or exceeds what’s required, the clause does nothing — claims pay in full, up to your limit, the way most owners assume insurance works. If you’re carrying less than required, every claim is reduced by the same proportion, regardless of how small the loss is.
The clause exists because insurers price a policy assuming you’re carrying close to the property’s full value. Carrying less lowers your premium, but it also means you’re effectively self-insuring the gap — and the formula below is how that self-insurance gets collected at claim time.
This article covers how a commercial property policy pays once you already have one. For help deciding which policies a business needs in the first place, see our guides to Business Insurance for LLCs and Small Business Insurance.
The Formula, One Step at a Time
The payment is: (insurance carried ÷ insurance required) × loss, then the deductible is subtracted, then the result is capped at your limit of insurance.
Step one — insurance required. Take your property’s value at the time of loss and multiply it by the coinsurance percentage on your declarations.
Step two — the ratio. Divide your limit of insurance (what’s carried) by the insurance required. If this is 100% or more, you’re compliant and the rest of this formula doesn’t apply.
Step three — apply the ratio to the loss. Multiply your loss amount by that ratio.
Step four — subtract the deductible. This happens after the ratio is applied, not before.
Step five — cap at the limit. The result can never exceed your limit of insurance, even on a larger loss.
COMPLIANT — limit meets the requirement
Property value at loss: $1,000,000. Coinsurance: 80% → required $800,000. Limit carried: $800,000. Ratio: 100%.
Loss: $100,000. Deductible: $1,000.
Paid: $100,000 − $1,000 = $99,000, capped at the $800,000 limit → $99,000.
SHORT — limit below the requirement
Property value at loss: $1,000,000. Coinsurance: 80% → required $800,000. Limit carried: $600,000. Ratio: 600,000 ÷ 800,000 = 75%.
Loss: $100,000. Deductible: $1,000.
$100,000 × 75% = $75,000. Minus the $1,000 deductible = $74,000, capped at the $600,000 limit → $74,000.
SUSPENDED — Agreed Value in effect
Property value at loss: $1,000,000. Agreed Value amount on declarations: $800,000. The coinsurance condition does not apply.
Loss: $100,000. Deductible: $1,000.
Paid: $100,000 − $1,000 = $99,000, capped at the $800,000 limit → $99,000.
| Scenario | Value at loss | Limit carried | Required | Ratio | Loss | Deductible | Paid |
|---|---|---|---|---|---|---|---|
| COMPLIANT | $1,000,000 | $800,000 | $800,000 | 100% | $100,000 | $1,000 | $99,000 |
| SHORT | $1,000,000 | $600,000 | $800,000 | 75% | $100,000 | $1,000 | $74,000 |
| SUSPENDED | $1,000,000 | $800,000 (Agreed Value) | — | — | $100,000 | $1,000 | $99,000 |
It Applies to Small Claims Too
The short scenario above never came near its limit. A $600,000 limit, a $100,000 loss — on paper, that looks like more than enough room. It paid $74,000 anyway.
Most owners picture coinsurance as a total-loss problem: burn the building down, and only then does the gap between what you carry and what the building is worth get exposed. That’s backwards. A total loss is capped at the limit either way, so the ratio barely matters once the loss is large enough. It’s the small and midsize claims — the kitchen fire, the roof collapse, the water damage — where the ratio does its full work, because there’s nothing else limiting the payment.
That’s why a policy can run for years without anyone noticing it’s underinsured. Nothing forces the issue until a claim is filed, and by then the percentage has already been applied.
Why a Policy Nobody Touched Falls Out of Compliance
Compliance is tested at the time of loss, using the property’s value on that day — not the value when the policy was written, and not the limit you chose five renewals ago.
Construction costs move. Two or three quiet years of material and labor inflation can raise a building’s rebuild cost enough to erase the buffer an 80% clause is meant to provide, even though the limit on the policy hasn’t changed and nothing about the building has either.
Inflation is an accelerant, not the only cause. A building that was underinsured on day one — because the original limit was based on a purchase price or a lender’s number rather than a rebuild-cost estimate — is exposed from day one, and inflation just widens a gap that was already there.
Either way, the only way to know where you stand is to compare your limit against a current rebuild-cost figure, not to assume last year’s number still holds.
The Three Valuation Settings
How your loss gets valued is a separate setting from the coinsurance percentage, and it’s chosen on the same declarations page.
Actual Cash Value (ACV)
Replacement cost minus depreciation. This is the default if replacement cost isn’t selected for an item. Depreciation reduces the payment further, on top of any coinsurance reduction. Nothing specific needs to appear on the declarations — ACV applies by default when replacement cost isn’t shown.
Replacement Cost
No deduction for depreciation on a covered loss. Must be selected explicitly for each item on the declarations — it is not automatic. The coinsurance percentage still applies the same way; this setting changes depreciation, not the coinsurance math.
Agreed Value
The only one of the three that changes the coinsurance condition itself — while in effect, it generally doesn’t apply. Requires an accepted Statement of Values and a declarations entry showing the amount and an expiration date. Can be written on either an ACV or replacement cost basis, and does not pay above the limit of insurance.
| Setting | How the loss is valued | Effect on depreciation | Effect on the coinsurance penalty | What must appear on declarations |
|---|---|---|---|---|
| Actual cash value | Replacement cost minus depreciation | Depreciation is deducted | No change — the percentage still applies | Nothing specific; this is the default |
| Replacement cost | Cost to repair or replace, no depreciation deduction | No depreciation deducted | No change — the percentage still applies | Replacement cost selected per item |
| Agreed Value | The agreed amount, on an ACV or RC basis | Depends on the basis chosen | Condition generally does not apply while in effect | Amount and expiration date, plus an accepted Statement of Values |
Only one of these three settings changes the coinsurance math itself. The other two change how depreciation is handled, not whether the percentage gets applied.
The Exit: the Agreed Value Option
Agreed Value is the recognized way to suspend the coinsurance condition rather than just manage around it.
It’s listed in the Optional Coverages section of the ISO Building and Personal Property Coverage Form (CP 00 10). When it’s shown on your declarations and in effect, the coinsurance condition generally does not apply — your payment isn’t reduced by a ratio, because there’s no longer a required amount to fall short of.
Getting there isn’t automatic. The insured submits a Statement of Values — typically ISO CP 16 15, ACORD 139, or an equivalent form — and the insurer has to accept it. Once accepted, the option has to actually appear on the declarations page, with a dollar amount and an expiration date. No entry, no suspension.
Two things it is not: it is not guaranteed replacement cost, and it does not pay above your limit of insurance. It can also be written on either an actual cash value or a replacement cost basis — those are a separate choice from Agreed Value itself, not a package deal.
And it expires. An Agreed Value entry without a current, in-force expiration date generally means the coinsurance condition is back in force, whether or not anyone remembered to renew it.
Where the Value Number Should Come From
The number that matters for this clause is what it would cost to rebuild the property today — not what it would sell for, not what’s on the books, and not what the county says it’s worth.
Market value reflects land, location, and what a buyer would pay — all things that have little to do with construction cost. Book value reflects depreciation schedules for accounting purposes. A tax assessment is set by a local authority on its own cycle and its own methodology. None of the three is a substitute for a professional replacement-cost estimate, and using one in place of the other is a common way a limit ends up wrong without anyone intending it.
| Figure | What it measures | Usable for this clause? |
|---|---|---|
| Replacement cost estimate | Cost to rebuild today | Yes — this is the correct figure |
| Market value | What a buyer would pay, including land | No |
| Purchase price | What you paid, at that date | No |
| Book value | Depreciated accounting value | No |
| Tax assessment | A local authority’s own valuation | No |
Your Declarations Page in Three Lines
Everything in this article comes down to three entries on one page — find them, and you know where you stand.
The Three-Line Declarations Check
- Open your declarations page and find the property or building section. Everything below is on that page or in the endorsement list.
- Line one — the coinsurance percentage. Usually shown as 80%, 90% or 100% beside the building limit. Write it down.
- Line two — Agreed Value. Look in Optional Coverages for an Agreed Value entry with an amount and an expiration date. If there’s no date in force, assume the coinsurance condition applies.
- Line three — the valuation basis. Look for “Replacement Cost” shown for each item. If it’s not shown, ask whether that item settles at actual cash value.
- Do the arithmetic: today’s rebuild cost × your percentage. Compare it to your limit.
- Get a real number for the rebuild cost. A professional replacement-cost estimate, not a market appraisal, not your purchase price, not the tax assessment. Ask who produced the figure currently on file and when.
- Ask your agent, in writing, four questions: what value is my limit based on and from what date; what would it cost to bring the limit to the requirement; is the Agreed Value Option available on this policy and what does it require; is replacement cost selected on every item.
- Put the answers in the file with the date, and repeat before each renewal.
- Don’t raise or lower a limit based on this article or the calculator alone — the figure has to come from a valuation.
| What to find | Where it usually appears | What it means if it’s missing |
|---|---|---|
| Coinsurance percentage | Beside the building limit, property section | A percentage is generally assumed even if not stated — ask your agent to confirm |
| Limit of insurance | Property or building section | N/A — this is always shown |
| Agreed Value option | Optional Coverages or endorsement list, with amount and expiration date | The coinsurance condition is presumed to apply |
| Replacement cost designation | Per item, property or valuation section | That item settles at actual cash value |
A certificate of insurance shows your limits to a lender or landlord — it does not show your valuation basis or your coinsurance percentage. A lender or landlord reading a COI cannot see this exposure. See our Certificate of Insurance guide for what a COI does and doesn’t prove.
If a Penalty Has Already Been Applied
This article explains the mechanism and what to request — it doesn’t assess whether any particular penalty was calculated correctly.
Ask your insurer, in writing, for four things: the property value it used and the date and source of that figure; the coinsurance percentage and limit it applied; the clause language it relied on; and the calculation itself, step by step, the way it’s laid out above.
A licensed public adjuster or a coverage attorney reviews disputed valuations and can tell you whether the figures used hold up — that’s a separate step from what this article covers, and the right one if something looks off once you have the numbers in writing.
Business interruption coverage carries its own, separate coinsurance mechanics based on projected earnings rather than property value. If the claim also involves lost income, see our Business Interruption Insurance guide for that calculation — it isn’t the one covered here.
FAQ
What triggers a coinsurance penalty?
Carrying a limit of insurance below what the coinsurance clause requires — your property’s value at the time of loss, times the percentage on your declarations. The penalty applies automatically once that gap exists; it doesn’t require a total loss or any particular kind of claim.
Does coinsurance apply to partial losses?
Yes, and this is the detail most owners miss. A small or midsize claim gets the full proportional reduction, because nothing else is limiting the payment the way the policy limit does on a large loss.
How is the penalty calculated?
(Limit carried ÷ insurance required) × loss, then the deductible is subtracted, then the result is capped at your limit of insurance. The calculator above walks through each step with your own numbers.
Is the deductible taken before or after the penalty?
After. The ratio is applied to the loss first, and the deductible is subtracted from that reduced figure — not from the original loss amount.
What does an 80% coinsurance clause mean?
Your limit has to equal at least 80% of your property’s value at the time of loss to avoid a penalty. Carry less than that, and every claim is reduced in proportion to how far short you are.
Is 80%, 90% or 100% better?
A higher percentage generally requires carrying more insurance relative to the property’s value, which can affect premium. This article doesn’t recommend a percentage — it’s a trade-off between premium and exposure that depends on your own numbers, and it’s worth discussing directly with your agent.
What is insurance required versus insurance carried?
Insurance carried is your limit of insurance, shown on the declarations. Insurance required is your property’s value at the time of loss multiplied by the coinsurance percentage. The clause compares the two.
Can the clause be removed?
The recognized way is the Agreed Value Option, which generally suspends the condition while an accepted Statement of Values and a current declarations entry are in place. It isn’t the same as the clause being deleted outright — it expires and has to be kept current.
What is the Agreed Value Option?
An optional coverage in the ISO Building and Personal Property Coverage Form that suspends the coinsurance condition once a Statement of Values is accepted by the insurer and the option is shown on the declarations with an amount and an expiration date.
Does Agreed Value mean my claim is paid in full?
It means the coinsurance ratio generally doesn’t reduce your payment. It does not mean you’re paid above your limit of insurance, and it doesn’t guarantee replacement cost unless replacement cost was also selected as the valuation basis.
What is a Statement of Values?
A form — typically ISO CP 16 15, ACORD 139, or an insurer’s equivalent — listing your property’s values, which the insurer reviews and has to accept before Agreed Value can take effect.
What’s the difference between replacement cost and Agreed Value?
Replacement cost is a valuation setting that removes the depreciation deduction on a covered item; it doesn’t change the coinsurance math. Agreed Value is the one that changes the coinsurance math itself, by suspending the condition. They can apply together or separately.
Will my policy pay actual cash value by default?
For any item where replacement cost isn’t explicitly selected on the declarations, yes — the default is actual cash value, meaning replacement cost minus depreciation.
Can I use my building’s market value?
No. Market value includes land and reflects what a buyer would pay, not what it costs to rebuild the structure. Using it here is a common way a limit ends up wrong.
Does my tax assessment matter?
Not for this clause. A tax assessment is set by a local authority on its own methodology and its own schedule, and it isn’t a rebuild-cost figure.
Does coinsurance appear in homeowners policies?
Rarely — it’s primarily a commercial property feature. See our guide on Homeowners Insurance and a Home Business for how personal and commercial forms differ if you’re running a business from a residence.
This is general information, not insurance or legal advice. It describes a standard industry form, and your policy may be written differently. Coverage outcomes depend on your policy wording, endorsements, the valuation determined at the time of loss, and applicable state law. Verified October 2026. Consult a licensed agent, public adjuster, or attorney about your own policy.
Last updated:
Daniel Hayes is the founder and sole researcher at AdvoraHQ. He covers U.S. personal finance, insurance, and consumer law — working directly from IRS publications, federal and state statutes, court opinions, and SEC filings rather than secondary summaries. His focus is the gap between what readers think they know and what the source documents actually say. Daniel is not a licensed attorney, CPA, or financial advisor; his articles are educational and not personalized advice. Reach him at Daniel.Hayes@advorahq.com.