
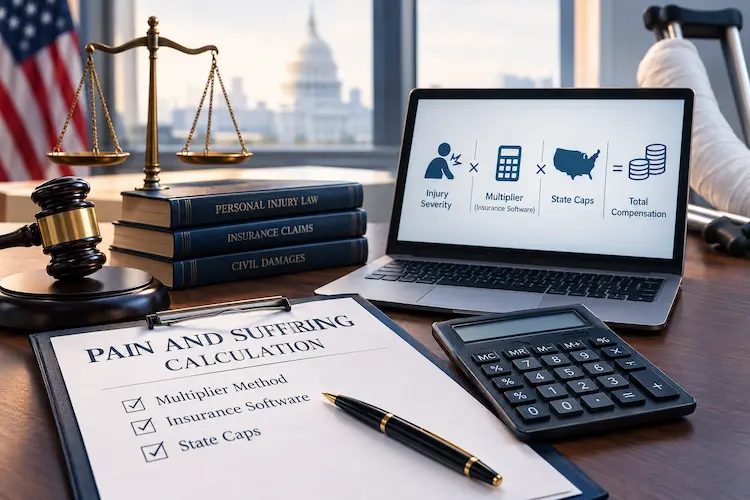
Quick answer. No law sets a formula for pain and suffering. Attorneys and adjusters use rough conventions — a multiple of your medical bills and lost wages, or a daily rate for each day of recovery — and many insurers run claims through evaluation software that scores your medical records. Your fault share, the other driver’s policy limits, and in a few states a legal cap can shrink the number before you ever see a check.
The single biggest thing you control is how completely and accurately your injuries are documented.
Get a realistic negotiation range for your claim →
Verified October 24, 2026. Caps and rules change — check your state’s statute.
Negotiation Range Estimator
This tool turns the common conventions into a rough negotiation range and then applies your fault share, the other driver’s policy limit, and a state cap if one applies. Enter numbers only — no names, claim numbers, or insurer names.
How This Guide Is Organized
Every section below is labeled with one of three tiers, so you can tell what is law, what is negotiation habit, and what is up to you.
What “Pain and Suffering” Covers
“Pain and suffering” is the everyday name for non-economic damages: compensation for how an injury changes your life, as opposed to the bills it creates.
Non-economic damages can include physical pain, emotional distress, loss of enjoyment of life, and inconvenience. Statutes list these differently. Ohio’s, for example, defines the category as non-monetary harm that includes pain and suffering, mental anguish, and disfigurement, among other intangible losses.
Economic damages are the losses with receipts: medical bills, lost income, and other out-of-pocket costs. They are documented, so they are the easier half of a claim to put a number on.
The Multiplier: Where It Comes From and Why It Isn’t Law
The multiplier is a negotiating shortcut — your economic damages times a number, commonly said to run from about 1.5 to 5 — and it is a convention, not law.
Attorneys and adjusters use it to start a conversation. The number chosen reflects how serious and lasting the injury looks, and that is argued, not calculated.
Juries are not handed a multiplier. California’s pattern jury instruction on non-economic damages (CACI No. 3905A) tells jurors that no fixed standard exists and to use their judgment and common sense. Look up your own state’s pattern instruction to see its wording.
Multiplier
What it is: economic damages × a number tied to how serious the injury looks.
Who uses it: attorneys and adjusters, as a starting point for negotiation.
Why it isn’t law: no statute requires it, and jurors are not told to use it. It is a convention.
Per diem
What it is: a daily dollar rate × the number of days of recovery.
Who uses it: attorneys, and sometimes adjusters, for injuries with a clear end date.
Why it isn’t law: the daily rate is chosen, not set by any rule. It is a convention.
Claim-evaluation software
What it is: a rules-based tool that turns injury details from your records into a suggested range.
Who uses it: many large auto insurers, reportedly.
Why it isn’t law: it is an insurer’s internal tool. It guides an offer and does not bind anyone.
| Method | How it works | Who uses it | Why it isn’t law |
|---|---|---|---|
| Multiplier | Economic damages × a number tied to how serious the injury looks | Attorneys and adjusters, as a negotiating starting point | No statute requires it and jurors are not told to use it. It is a convention. |
| Per diem | A daily dollar rate × days of recovery | Attorneys, and sometimes adjusters, for injuries with a clear end date | The rate is chosen, not set by any rule. It is a convention. |
| Claim-evaluation software | Rules turn injury details from medical records into a suggested range | Many large auto insurers, reportedly | It is an insurer’s internal tool. It guides an offer and binds no one. |
Two people can arrive with identical bills and leave with very different offers. The difference usually comes from the records, the length of treatment, the fault dispute, the policy limits, and how the claim is presented. A single multiplier hides all of that.
It also rewards bigger bills, which says little about how much a person is actually hurting.
The Per Diem Method
Per diem means “by the day”: a dollar figure for each day of recovery, multiplied by the number of days.
The daily rate is often tied to the person’s daily income. That is a convention, not law, and nothing requires it.
As arithmetic only: a $200 daily rate for 90 days gives $18,000. Those numbers are an illustration, not a typical amount.
The method fits shorter injuries with a defined end date. It breaks down in three places:
- For long or permanent injuries, the “days” run for years, and a daily figure stops making sense.
- The daily rate is a choice, so two people can reach very different totals from the same facts.
- A rate tied to income undervalues pain for people who earn little, are retired, or are students. Income does not measure how much someone suffers.
How Insurers Actually Score Your Claim
Many large auto insurers use claim-evaluation software, such as Colossus, to turn the injury details in your medical records into a suggested range for general damages.
Colossus was developed by CSC (Computer Sciences Corporation) and is licensed to insurers. According to the Consumer Federation of America (CFA), an adjuster reads the medical records and picks from roughly 600 injury codes. Each code carries a severity value, the insurer assigns a dollar amount to each point of severity, and the software returns a range for general damages.
This is a rules-based tool: details go in, a range comes out. Inputs matter, which is why the records matter.
CFA also notes that these systems evaluate general damages, such as pain and suffering. They are not used to estimate medical bills or lost wages, or to settle fault questions like comparative negligence.
Consistent treatment vs. gaps
Why it matters (as reported): gaps can look like recovery or like a different cause for ongoing symptoms.
Accurate documentation: follow the treatment plan. If you pause or stop, write down why: cost, transport, work, or a provider’s advice.
Objective findings vs. complaints only
Why it matters (as reported): imaging and exam findings give the software and the adjuster something concrete to code.
Accurate documentation: ask for complete imaging reports and exam notes. Describe your symptoms fully and truthfully either way.
Documented daily limitations
Why it matters (as reported): plaintiff-side practice guides describe “duties under duress” as a recognized category: activities a person keeps doing despite pain.
Accurate documentation: tell providers what you cannot do, or can do only with pain, and ask that it be noted. Keep a dated daily log.
Prior injuries
Why it matters (as reported): earlier injuries to the same body part can change how an injury is coded and how much is attributed to the crash.
Accurate documentation: be upfront about your history. Records that separate old from new help more than silence does.
Delay before first treatment
Why it matters (as reported): a long delay can lead an insurer to question whether the injury came from the crash.
Accurate documentation: get care promptly. If you waited, say why in your records.
Table 2. What tends to raise or lower an insurer’s evaluation, as reported by CFA and plaintiff-side practice guides (see Sources). These are reported tendencies, not rules. Verified October 24, 2026.
| Factor | Why it matters (as reported) | What accurate documentation looks like |
|---|---|---|
| Consistent treatment vs. gaps | Gaps can look like recovery or like a different cause for ongoing symptoms. | Follow the treatment plan. If you pause or stop, write down why: cost, transport, work, or a provider’s advice. |
| Objective findings vs. complaints only | Imaging and exam findings give the software and the adjuster something concrete to code. | Ask for complete imaging reports and exam notes. Describe your symptoms fully and truthfully either way. |
| Documented daily limitations | Plaintiff-side practice guides describe “duties under duress” as a recognized category: activities a person keeps doing despite pain. | Tell providers what you cannot do, or can do only with pain, and ask that it be noted. Keep a dated daily log. |
| Prior injuries | Earlier injuries to the same body part can change how an injury is coded and how much is attributed to the crash. | Be upfront about your history. Records that separate old from new help more than silence does. |
| Delay before first treatment | A long delay can lead an insurer to question whether the injury came from the crash. | Get care promptly. If you waited, say why in your records. |
“Duties under duress.” This is a term from the Colossus system. Trial Guides, a publisher for plaintiffs’ trial lawyers, describes it as covering activities a person kept performing despite pain, which generally need to appear in the medical records. If you work, lift, or care for a child through pain, that is a fact your records should show, if it is true.
What consumer advocates have warned. In a consumer alert, CFA warned that automated systems can produce unfairly low offers and alleged that some insurers adjust their settings to reduce payments. The alert carries no printed date; it describes an August 27, 2010 multistate agreement with Allstate, so it was written after that. In a dated report, “Low Ball” (June 4, 2012), CFA and a former Colossus expert at Allstate made similar claims. CFA reported that CSC and its competitors describe these tools as a way to evaluate claims more consistently. These are an advocacy group’s allegations, and insurers describe their tools differently.
What is only “reportedly” true. Some plaintiff law firms say the software also weighs where a claim would be tried and the history of the attorney involved. We could not confirm either claim from an independent source, so treat them as unverified.
CFA’s alert suggests that you ask the insurer whether a computerized system was used to reach the offer. If you do not get a clear answer, you can file a complaint with your state insurance department.
The Order That Shrinks the Number
Five things happen in order — your range, then your fault share, then the policy limit, then any cap, then taxes — and the middle three often matter more than any formula.
- Value range. The multiplier, per diem, or the insurer’s software produces a starting range. (THE NEGOTIATION)
- Your fault share. Your share of fault reduces the number. Pure comparative systems reduce it by your percentage. Modified systems bar recovery once your fault reaches a set bar, either 50% or 51%. A few jurisdictions use contributory negligence, where even a small share of fault can bar recovery. (THE LAW) Details: Partially at Fault in an Accident.
- Policy limits. The at-fault driver’s bodily-injury liability limit is often the practical ceiling on what their insurer pays. Your own uninsured/underinsured motorist (UM/UIM) coverage may add to it. (THE LAW and your policy) Details: Uninsured Motorist Coverage.
- Any cap. A few states cap non-economic damages. Most do not. Caps cover non-economic damages only, and states differ on whether a cap is applied before or after fault is subtracted. (THE LAW)
- Taxes. Federal rules treat each part of a settlement differently. (THE LAW)
Attorney fees and medical liens come after all of this. To see what you would actually keep, use the partner article How Much of My Settlement Will I Keep?.
States That Cap Pain and Suffering — and Caps That Were Struck Down
Most states have no general cap on pain and suffering, a few do, and several caps that older lists still show have been struck down by courts.
Colorado: $1.5 million
Applies to: non-economic damages in personal-injury cases filed on or after January 1, 2025 — regardless of when the injury happened. HB 24-1472 decoupled the cap from the accrual date, so it is the filing date alone that controls. Wrongful death has its own cap ($2.125 million).
Source: C.R.S. § 13-21-102.5(3)(a)(II), as amended by HB 24-1472.
Adjustment: inflation adjustments begin January 1, 2028 and repeat every two years. Cases filed before 2025 were governed by lower limits.
Verified: October 24, 2026, from the enacted bill text.
Maryland: $980,000 (from Oct. 1, 2026)
Applies to: personal-injury causes of action arising October 1, 2026 – September 30, 2027. The amount was $965,000 for October 1, 2025 – September 30, 2026. It rises $15,000 each October 1, based on the date the cause of action arose.
Also: applies per direct victim. Juries are not told of the cap. In wrongful death with two or more beneficiaries, the limit is 150% of the amount.
Source: Md. Code, Cts. & Jud. Proc. § 11-108(b), (d). Malpractice is separate (§ 3-2A-09).
Verified: October 24, 2026, from the statute text.
Ohio: greater of $250,000 or 3× economic loss
Applies to: most tort claims, up to $350,000 per plaintiff or $500,000 per occurrence. No cap for permanent and substantial physical deformity, loss of use of a limb, or loss of a bodily organ system, or for a permanent physical functional injury that permanently prevents caring for oneself and performing life-sustaining activities.
Excluded: medical claims, wrongful death actions, and certain government defendants.
Source: Ohio R.C. § 2315.18(B)(2)–(3), (H).
Verified: October 24, 2026, from the statute text.
Oklahoma: struck down 2019
What happened: on April 23, 2019, the Oklahoma Supreme Court held the $350,000 non-economic cap an unconstitutional special law.
Case: Beason v. I.E. Miller Services, Inc., 2019 OK 28, 441 P.3d 1107.
Verified: October 24, 2026.
Kansas: struck down 2019 (personal injury)
What happened: in an opinion filed June 14, 2019, the Kansas Supreme Court held the cap in K.S.A. 60-19a02 violated the jury-trial right in personal-injury actions. Separate wrongful-death caps were not directly addressed.
Case: Hilburn v. Enerpipe Ltd.
Verified: October 24, 2026.
| State | Cap | Applies to | Statute or case | Verified |
|---|---|---|---|---|
| Colorado | $1.5 million | Personal-injury cases filed on or after January 1, 2025, regardless of when the injury happened — HB 24-1472 decoupled the cap from the accrual date, so filing date alone controls. Inflation adjustments begin January 1, 2028. Wrongful death has its own cap ($2.125 million). | C.R.S. § 13-21-102.5(3)(a)(II); HB 24-1472 | October 24, 2026 (bill text) |
| Maryland | $980,000, or $965,000 for earlier accidents | Causes of action arising October 1, 2026 – September 30, 2027 ($980,000); October 1, 2025 – September 30, 2026 ($965,000). Rises $15,000 each October 1. Per direct victim. Juries are not told. | Md. Code, Cts. & Jud. Proc. § 11-108(b), (d) | October 24, 2026 (statute text) |
| Ohio | Greater of $250,000 or 3× economic loss, up to $350,000 per plaintiff / $500,000 per occurrence | Most tort claims. No cap for permanent and substantial physical deformity, loss of use of a limb or bodily organ system, or a permanent physical functional injury that prevents independent self-care. Excludes medical claims and wrongful death. | Ohio R.C. § 2315.18(B)(2)–(3), (H) | October 24, 2026 (statute text) |
| Oklahoma — struck down 2019 | None currently from the former $350,000 cap | Former cap on non-economic damages in personal-injury cases, held an unconstitutional special law on April 23, 2019 | Beason v. I.E. Miller Services, Inc., 2019 OK 28, 441 P.3d 1107 | October 24, 2026 |
| Kansas — struck down 2019 (personal injury) | None currently from the former K.S.A. 60-19a02 cap | Held to violate the jury-trial right in personal-injury actions (opinion filed June 14, 2019). Separate wrongful-death caps were not directly addressed. | Hilburn v. Enerpipe Ltd.; K.S.A. 60-19a02 | October 24, 2026 |
Why older lists get this wrong. Many “caps by state” pages were written before the 2019 rulings and never updated. Many also mix malpractice caps in with general caps, which is why the numbers conflict from page to page.
What a cap does. A cap limits what a court will enter on a verdict for non-economic damages. In Maryland and Ohio, juries are not told of the cap, and the court reduces an award that exceeds it. Kansas shows how this worked before the ruling: in Hilburn, a jury found $301,509.14 in non-economic damages and the trial court cut it to $250,000 under the statute, before the Kansas Supreme Court held the cap unconstitutional. The cap rarely decides a small claim, but it is why large claims look different in different states.
Oregon. In Busch v. McInnis Waste Systems, Inc., 366 Or 628 (July 9, 2020), the Oregon Supreme Court held that applying the $500,000 cap in ORS 31.710(1) to that plaintiff violated the state constitution’s remedy clause. The court said its decision was limited to the circumstances of that case, so how far it reaches is a legal question we do not resolve here. We do not list Oregon as a cap state or as a struck-down state.
Other states. A number of other states are reported to have their own general caps. We list a state only after reading its statute, so check yours. Maryland’s repeal bill for 2026 (SB 474) did not pass, according to bill-tracking records, so the annual increases continue.
Medical malpractice is a separate system. Many more states cap malpractice damages, often at different amounts and on different schedules. Ohio’s general cap statute excludes medical claims, and Maryland’s malpractice cap sits in a different section (§ 3-2A-09). See Medical Malpractice for that system.
Is Pain and Suffering Taxable?
Under federal law, damages for personal physical injuries are generally not taxable, but punitive damages and interest are, and emotional-distress damages that do not come from a physical injury can be.
Physical-injury damages (not punitive)
Generally taxable? No, if you did not deduct related medical expenses in earlier years.
Source: IRC § 104(a)(2); IRS Pub. 4345.
Emotional distress from a physical injury
Generally taxable? No. Treated the same as the physical injury.
Source: IRS Pub. 4345.
Emotional distress without a physical injury
Generally taxable? Yes, reduced by related medical expenses not previously deducted.
Source: IRS Pub. 4345.
Punitive damages
Generally taxable? Yes, even in a physical-injury settlement.
Source: IRS Pub. 4345.
Interest
Generally taxable? Yes, as interest income.
Source: IRS Pub. 4345.
Previously deducted medical expenses
Generally taxable? Yes, to the extent the deduction gave you a tax benefit.
Source: IRS Pub. 4345.
Table 4. Which parts of a settlement are taxable (federal). Source: IRS Publication 4345 (Rev. 9-2023) and IRC § 104(a)(2). Verified October 24, 2026.
| Component | Generally taxable? | Source |
|---|---|---|
| Physical-injury damages (not punitive) | No, if you did not deduct related medical expenses in earlier years | IRC § 104(a)(2); IRS Pub. 4345 |
| Emotional distress from a physical injury | No. Treated the same as the physical injury | IRS Pub. 4345 |
| Emotional distress without a physical injury | Yes, reduced by related medical expenses not previously deducted | IRS Pub. 4345 |
| Punitive damages | Yes, even in a physical-injury settlement | IRS Pub. 4345 |
| Interest | Yes, as interest income | IRS Pub. 4345 |
| Previously deducted medical expenses | Yes, to the extent the deduction gave you a tax benefit | IRS Pub. 4345 |
A settlement can have several parts. The IRS generally will not disturb an allocation between them if it matches the substance of the settled claims, so how the agreement is written matters. A tax professional can review yours.
For the take-home calculation after fees and liens, see How Much of My Settlement Will I Keep?.
How to Document Pain and Suffering Accurately
Accurate, complete, dated records are the only reliable way to make sure the insurer’s file matches what actually happened to you.
- Get care promptly and follow the treatment plan. If you stop or pause treatment, write down why (cost, transport, work).
- Tell every provider all your symptoms, including pain that comes and goes, sleep problems, and anxiety. Accuracy, not intensity.
- Tell providers what you can’t do, or can do only with pain — work tasks, childcare, driving, chores. Ask that it be noted in your record.
- Keep a short daily log: pain level, activities missed, help you needed. Date every entry.
- Save every bill, receipt, mileage record, and pay stub showing missed work.
- Photograph visible injuries over time.
- Request complete records, including physical therapy notes and imaging reports, before you negotiate.
- Be careful with statements and social media. See Already Gave a Recorded Statement and What to Do After a Car Accident.
- Never exaggerate. Inconsistent records hurt claims, and false statements can be fraud.
Do not ask a doctor to use particular phrases. Tell your providers the truth, completely, and let them record what they observe.
When the Offer Seems Low — and When to Get a Lawyer
If an offer seems low, first find out what records the insurer has and whether anything is missing, then decide whether you need a lawyer.
- Ask what the offer is based on. Ask which records the adjuster has and which injuries were considered. Ask in writing so there is a record.
- Fill in missing records. If therapy notes, imaging, or a provider’s explanation of a treatment gap never reached the file, send them.
- Put your response in writing. A written demand generally lays out the facts of the crash, your treatment timeline, your bills and lost income, and how the injuries affect your daily life, with documents attached and a date for a reply. Keep it factual.
- Watch your deadlines. Filing deadlines vary by state; see Statute of Limitations by State.
Red flags that mean you should talk to a lawyer
- You have a lasting or permanent injury.
- Fault is disputed, or the insurer says you share it.
- You do not understand the offer or the release you are asked to sign.
- The insurer wants a release before your treatment is finished.
- Your damages may exceed the other driver’s policy limits.
- You have been asked for a recorded statement. See Already Gave a Recorded Statement.
Personal-injury lawyers commonly work for a contingency fee, a percentage of the recovery, which affects what you keep. See How Much of My Settlement Will I Keep? and Car Accident Lawyer. Whether to hire one is your decision.
If you already signed a release, see Settlement Check After Signing Release.
Frequently Asked Questions
How is pain and suffering calculated?
No law sets one method. Attorneys and adjusters use conventions such as a multiplier or a daily rate, many insurers use evaluation software, and a jury decides a verdict by judgment under its state’s instructions.
Is there a pain and suffering formula?
No. California’s pattern jury instruction (CACI No. 3905A) says no fixed standard exists for deciding the amount. Check your state’s pattern instruction for its wording.
What multiplier do insurance companies use?
There is no single multiplier. A range of about 1.5 to 5 is commonly cited, but that is a negotiating convention, not law, and many insurers rely on software rather than a stated multiple.
What is the per diem method?
A daily dollar rate multiplied by days of recovery. It is a convention, and it works poorly for long or permanent injuries.
How do insurance adjusters calculate pain and suffering?
Many adjusters enter injury information from your medical records into evaluation software, which returns a suggested range. Adjusters also weigh fault, policy limits, and their own judgment.
What is Colossus?
Colossus is claim-evaluation software developed by CSC and licensed to insurers. According to CFA, adjusters choose from roughly 600 injury codes, and the software returns a range for general damages.
What are “duties under duress”?
It is a term from the Colossus system for daily activities a person keeps doing despite pain. Plaintiff-side practice guides say these generally need to appear in the medical records.
Why is my injury settlement offer so low?
Common reasons include incomplete records, gaps in treatment, a fault share, a low policy limit, and the range an evaluation tool returned. Ask what the offer is based on, check the file for missing records, and consider a lawyer if the injury is lasting.
Can I get pain and suffering without broken bones?
Pain and suffering is not limited to fractures, and soft-tissue injuries can qualify. Consistent treatment and records of your limitations matter. Some no-fault states require an injury to meet a legal threshold before you can claim pain and suffering from another driver.
Does a gap in treatment lower my claim?
It can, because a gap may be read as recovery or as a different cause. If you paused for a real reason such as cost, transport, or work, make sure that reason is recorded.
How does my share of fault affect pain and suffering?
It reduces the amount, or bars recovery, depending on your state’s system. See Partially at Fault in an Accident.
What if my damages exceed the other driver’s policy limits?
The other driver’s insurer generally pays no more than the policy limit. Your own UM/UIM coverage may apply, and a lawyer can explain other options. See Uninsured Motorist Coverage.
Which states cap pain and suffering?
Most do not have a general cap. Of the states whose statutes we have read, Colorado ($1.5 million), Maryland ($980,000 for causes arising from October 1, 2026), and Ohio (greater of $250,000 or three times economic loss, up to $350,000 per plaintiff, with exceptions) do. See the table above.
Does Oklahoma or Kansas cap pain and suffering?
Not under the old caps. Oklahoma’s $350,000 cap was struck down on April 23, 2019 (Beason), and Kansas’s cap was held unconstitutional in personal-injury actions on June 14, 2019 (Hilburn). Check for newer legislation or rulings that apply to your claim.
Are juries told about damage caps?
Not in Maryland (§ 11-108(d)) or Ohio (R.C. 2315.18(F)(2)). The court reduces an award that exceeds the cap. Other states vary.
Is pain and suffering taxable?
Generally not when it comes from a personal physical injury. Punitive damages and interest are taxable. See Table 4 above.
Is emotional distress taxable?
If it comes from a physical injury, generally no. If it does not, it is taxable, reduced by related medical expenses not previously deducted.
Do I need a lawyer to get pain and suffering?
You are not legally required to hire one to settle with an insurer. Consider one if you have a lasting injury, fault is disputed, or you do not understand the offer.
Sources
- IRS, Publication 4345, Settlements — Taxability (Rev. 9-2023); Internal Revenue Code § 104(a)(2)
- Colorado HB 24-1472 and C.R.S. § 13-21-102.5
- Maryland Courts & Judicial Proceedings § 11-108
- Ohio Revised Code § 2315.18
- Beason v. I.E. Miller Services, Inc., 2019 OK 28, 441 P.3d 1107 (Okla. Apr. 23, 2019)
- Hilburn v. Enerpipe Ltd. (Kan. opinion filed June 14, 2019)
- Busch v. McInnis Waste Systems, Inc., 366 Or 628 (2020)
- Consumer Federation of America, consumer alert on computerized bodily-injury claims systems (undated; written after August 2010) and “Low Ball” report release (June 4, 2012)
- Trial Guides, “How Do Duties Under Duress Claims Impact Settlement Offers?”
- Judicial Council of California, CACI No. 3905A (Physical Pain, Mental Suffering, and Emotional Distress)
Last updated:
This article is general information, not legal or tax advice. No formula determines pain-and-suffering damages. The ranges shown are conventions and estimates, not valuations. Caps, fault rules, and tax treatment depend on your state, your facts, and current law, and were verified on October 24, 2026. Consult a licensed attorney about your claim.

Daniel Hayes is the founder and sole researcher at AdvoraHQ. He covers U.S. personal finance, insurance, and consumer law — working directly from IRS publications, federal and state statutes, court opinions, and SEC filings rather than secondary summaries. His focus is the gap between what readers think they know and what the source documents actually say. Daniel is not a licensed attorney, CPA, or financial advisor; his articles are educational and not personalized advice. Reach him at Daniel.Hayes@advorahq.com.
